


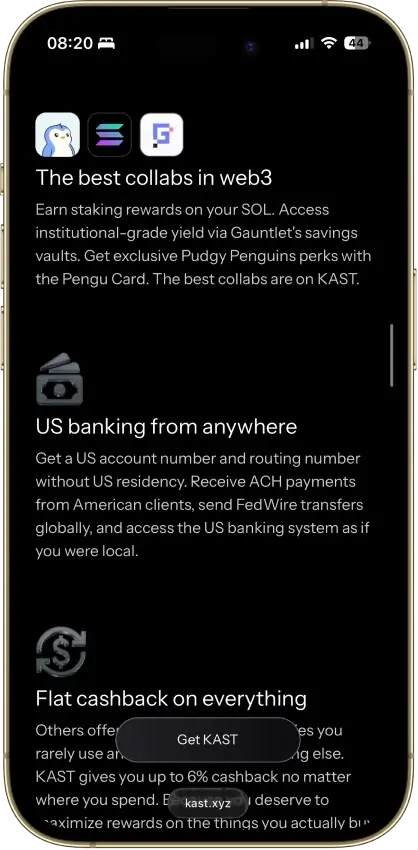
- Virtual US bank numbers for ACH and wires
- Free instant transfers to other KAST users
- Rewards paid in dollars, not a house token
Kast Card Overview
- Crypto Card Name
- Kast Card
- Card Type
- Prepaid
- Network
- Visa
- Digital Wallets
- Apple Pay, Google Pay
Additional details
- Availability
- 170+ countries, varies by jurisdiction.
- Rewards
- Standard earns 1.5% USD cashback on up to $2,000 of eligible monthly spending. Premium earns 2% on up to $10,000 and Private earns 3% on up to $40,000. Premium also earns 1% KAST Points and Private 2%.
- Fees
- Standard: $0; Premium: $1,000/year; Private: $10,000/year; FX fee: 0.5%–1.75%; ATM withdrawal: $3 + 2% + operator fees; top-up fee: stablecoin 0%, ACH $2, FedWire $15; inactivity fee: $1/month after 12 months; declined transaction fee: $0.50.
- Daily Spend / ATM Limit
- No spending limits; up to $250 per withdrawal and $750 per 24-hour period, up to three withdrawals
- Funding Source
- Bank Transfer, Onchain Wallet.
- Virtual Card & Shipping
- Instant virtual card, 7 to 10 business days for physical card
Kast Card Screenshots
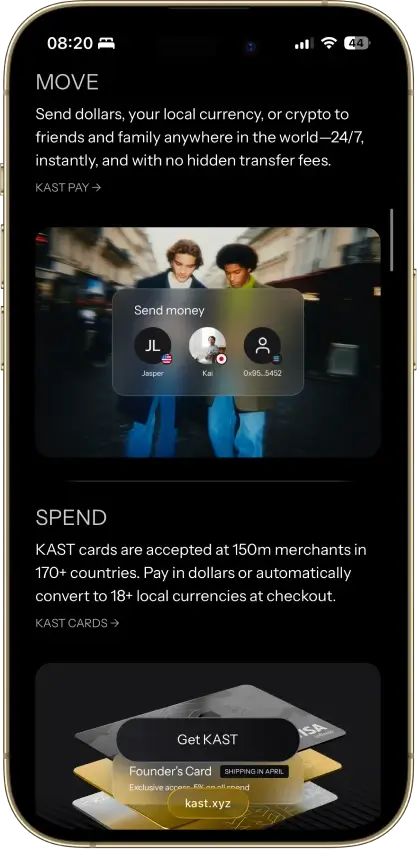
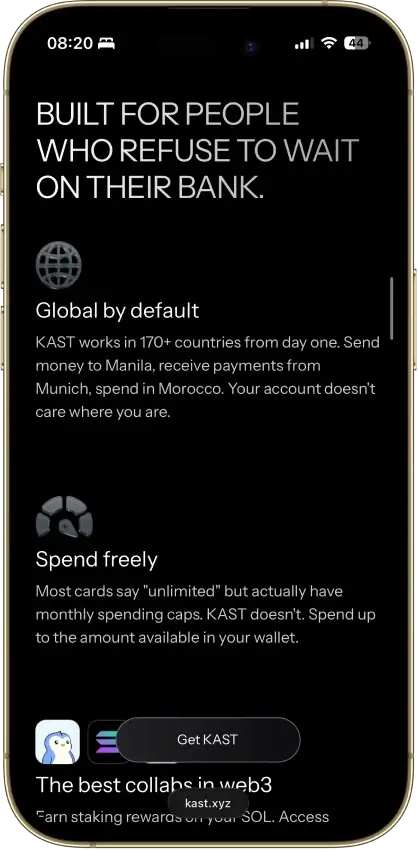
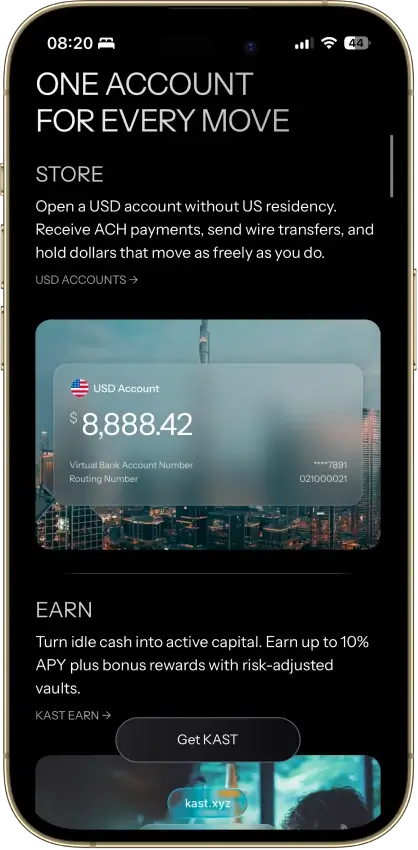
Screenshot 1 of 8
Kast Card Pros and Cons
Pros
- 1.5% back on the free membership
- Stablecoins load at par with no spread
- Virtual card ready minutes after sign-up
- No limit on card purchases
- Five stablecoins across major chains
Cons
- Volatile crypto is sold on deposit at 2%–5%
- Free-tier cashback stops at $2,000 a month
- ATM cash costs $3 plus 2%, limit $750 a day
- Top cashback rates cost $1,000–$10,000 a year
- No listed chargeback fees or timelines
What This Card Actually Is and How Spending Works
KAST's prepaid Visa spends a USD balance created when you deposit crypto. The funding model splits into two paths with very different costs. Stablecoins (USDT, USDC, USDe, PYUSD, RLUSD) credit 1:1 with a 0% deposit fee. Volatile coins (BTC, ETH, SOL, XRP, BNB) are sold to KAST the moment they arrive, at a 2% to 5% conversion rate that varies by token.
KAST holds the balance throughout, with deposited crypto treated as sold on entry. There is no self-custody fallback, and depositing volatile crypto creates a taxable disposal before any purchase. After KYC, a virtual card issues within minutes and can link to Apple Pay and Google Pay immediately.
Who KAST Is Best For — And Who Should Skip It
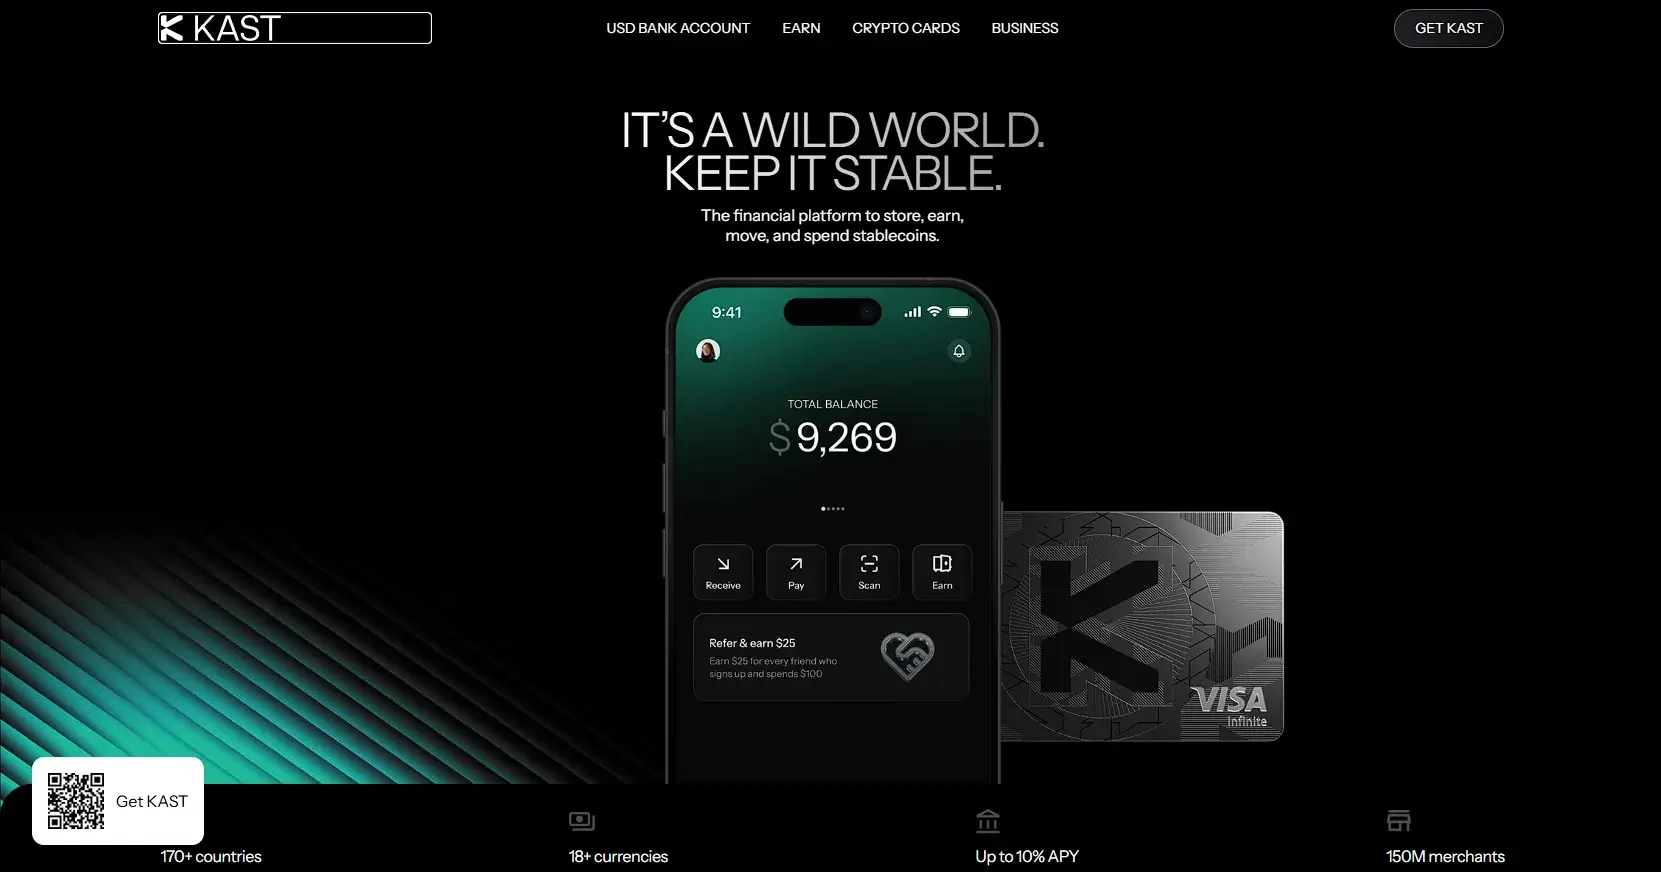
The card suits people who hold stablecoins and want to spend them at Visa merchants without an off-ramp to a bank. Residents of the US and other markets within the 170+ supported countries can load stablecoins at 0% and earn 1.5% in dollars without an annual card fee. Users paid in USDT or USDC, from freelancers to remote workers banking around a weak local currency, can spend those balances directly.
BTC and ETH holders pay 2% to 5% when their deposits are sold, reducing the value of subsequent cashback. Heavy cash users hit the $750-a-day ATM ceiling and the $3 + 2% fee on every withdrawal. Residents of the 49 restricted markets, including Canada, Australia, and Japan, cannot open an account at all.
Rewards Mechanics
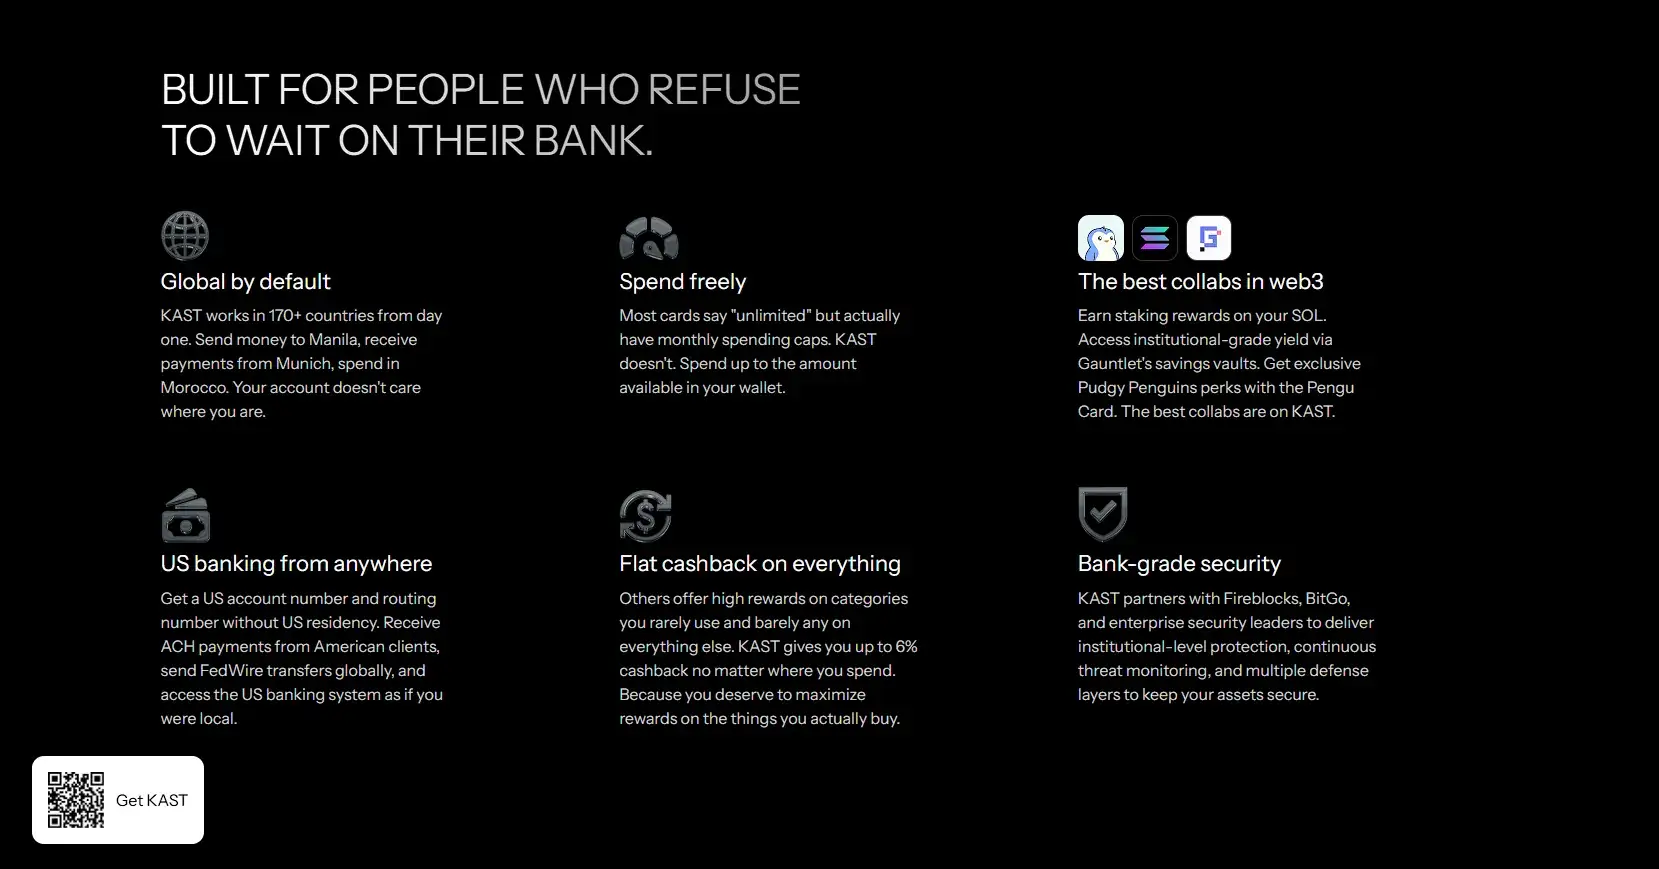
The realized reward on the free tier is 1.5% cashback, paid in USD to the card balance, on the first $2,000 of card spend each month. That works out to a maximum of $30 a month, or $360 a year, at zero annual cost. The rate requires no token lockup and pays in dollars. Seasonal multipliers no longer apply.
| Element | Value | Notes |
|---|---|---|
| Base rate (Standard) | 1.5% cashback in USD | Free tier, on the first $2,000 of monthly card spend, up to $30/month or $360/year |
| Top rates | Premium 2% on up to $10,000/month · Private 3% on up to $40,000/month | Premium $1,000/year, Private $10,000/year |
| Reward currency | USD, paid to the card balance | No volatile payout asset |
| Payout cadence | Per eligible spend | No token lockup, no seasonal multiplier |
| Caps and minimums | Standard $2,000/month · Premium $10,000/month · Private $40,000/month | Caps on rewarded monthly spend |
| Secondary layer | KAST Points on paid tiers, 1% Premium and 2% Private | Convertible toward the MOVE token |
Premium ($1,000 a year) lifts the rate to 2% on up to $10,000 of monthly spend, and Private ($10,000 a year) pays 3% on up to $40,000. Both paid tiers add KAST Points on top (1% and 2% on eligible spend) and both come on a Visa Infinite card with up to $1.5 million in travel accident insurance, purchase and price protection, and access to 1,200+ airport lounges. Counting cashback alone, Premium beats Standard above roughly $5,700 in monthly spending. Private beats Premium above roughly $32,000 a month.
KAST Points are an additional reward convertible toward the MOVE token. They should be assessed separately from dollar cashback. The retired structure (Limited and Luxe cards, and the Season 5 points rates of 2% to 8% that ended March 31, 2026) is gone, and older writeups quoting an 8% headline describe a product KAST no longer sells.
Fees and Pricing
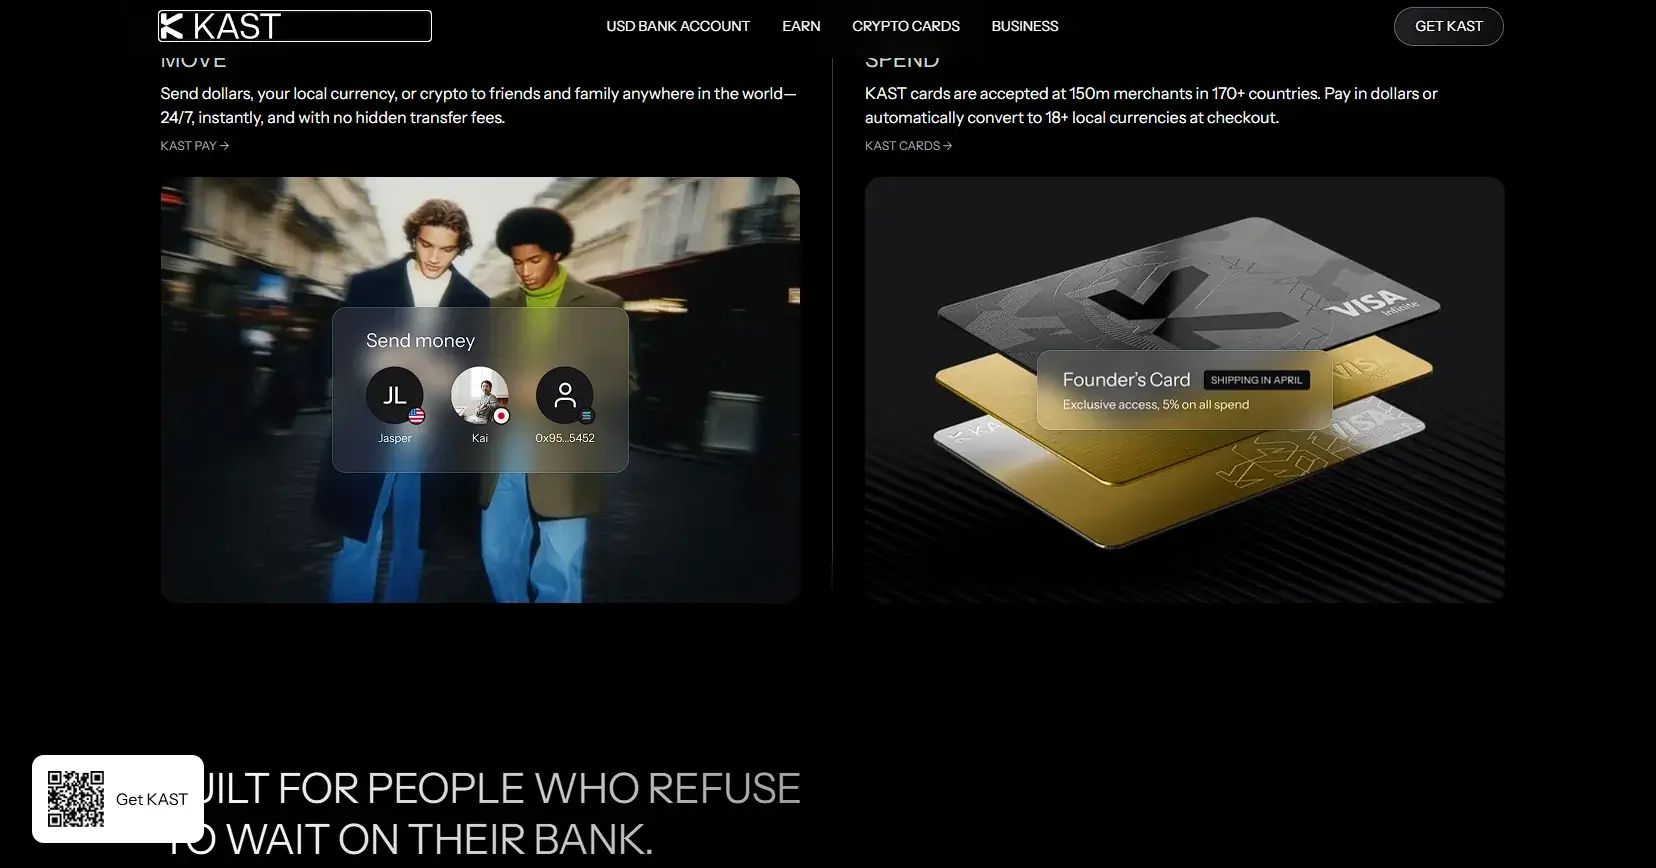
Standard has no opening or annual fee, and stablecoin deposits cost 0%. Other funding methods and some transactions carry the charges below.
| Fee or charge | Amount / rate | When it applies | Notes |
|---|---|---|---|
| Membership | $0 Standard · $1,000/yr Premium · $10,000/yr Private | Ongoing | |
| Card spend in USD | 0% | USD purchases | |
| FX fee | 0.5%–1.75% | Non-USD spend | |
| ATM | $3 + 2% per withdrawal | Cash withdrawal | Plus the FX fee on non-USD cash and any operator charge |
| Volatile-crypto deposit | 2%–5% auto-conversion | BTC, ETH, SOL, XRP, BNB deposits | Varies by token |
| Fiat top-up | $2 by ACH · $15 by FedWire | Fiat deposit | Stablecoin deposits free |
| Physical card | $40 shipping on Standard, included with Premium and Private | Card issuance | 7–10 business days |
| Virtual cards | First two free on Standard, then $2 each | Card issuance | |
| Small non-USD transactions | $0.10 | Purchases under $25 | |
| Declined transaction | $0.50 | Insufficient balance | |
| Inactivity | $1 a month | After 12 months dormant | |
| Stablecoin withdrawal | $0.20–$6 plus 0.1% | On-chain withdrawal | Depends on network, $5 minimum |
Fund with stablecoins and spend in USD, and the card runs close to free while paying 1.5%. Foreign-currency spending and ATM withdrawals add fees, as does funding with volatile crypto. A $1,000 BTC deposit can lose $20 to $50 before it becomes spendable balance.
Limits, Purchase and ATM
KAST publishes no card transaction limit or deposit and balance cap, so those limits do not require a tier upgrade. Monthly spending earns cashback up to $2,000 on Standard, $10,000 on Premium and $40,000 on Private. Spending above the applicable cap earns no reward.
ATM withdrawals are capped at $250 each and three withdrawals or $750 per rolling 24 hours. Each costs $3 + 2% before operator fees. Anyone planning regular ATM use should price that ceiling first.
| Limit | Amount | Notes |
|---|---|---|
| Card spending | No published ceiling | No card transaction limit, no deposit or balance cap |
| Cashback caps (rewarded monthly spend) | Standard $2,000 · Premium $10,000 · Private $40,000 | Spend past the cap still works, it earns nothing |
| ATM per withdrawal | $250 | Costs $3 + 2% before operator fees |
| ATM per rolling 24 hours | Three withdrawals or $750 |
Eligibility and Availability
KAST is live in 170+ countries and open to new applicants, including US residents. The app issues virtual US bank account numbers for receiving ACH and FedWire payments, with some state-level limits on that banking feature shown in-app. The signup process takes minutes.
- Download the app and register.
- Pass Sumsub KYC with a government ID and a selfie, which takes about two minutes and requires no credit check.
- Receive the virtual card within minutes of approval.
- Order a physical card if wanted ($40 shipping on Standard, 7 to 10 business days).
Physical delivery has its own coverage list of about 180 markets, including the US, UK, and Hong Kong. If KAST does not ship to a country, the virtual card and wallet features are the product there.
Restricted Countries
KAST publishes country eligibility only inside its signup flow, and the terms reserve the right to change “Restricted Locations” without notice. The list below is compiled from KAST's terms, its published card-shipping coverage, and third-party card listings, not from a single issuer page. Confirm in-app before planning around it.
Singapore is absent from KAST's shipping coverage and marked unsupported by multiple 2026 sources, so it is treated as restricted here. Hong Kong appears on KAST's own shipping list and is treated as supported, though one third-party listing disputes it.
Funding Rails
Five stablecoins load at 1:1 with no deposit fee. USDT and USDC are supported across major chains, so picking a cheap network (such as TRON or Solana) keeps the entire loading cost at the chain fee. KAST supports a wide network set overall; confirm the exact chain for any given coin in-app before depositing, since sending on an unsupported network risks loss.
Deposits of BTC, ETH, SOL, XRP and BNB are sold to KAST on arrival for a 2% to 5% conversion charge. This closes the crypto position and creates a taxable disposal in most jurisdictions. Fiat comes in by ACH ($2) or FedWire ($15) through the US virtual account numbers, and stablecoins go back out on-chain for $0.20 to $6 plus 0.1% depending on network.
Security, Custody, and Freeze Risk
KAST holds the USD balance and treats deposited crypto as sold on entry. Recovering those funds depends on KAST and its banking partners, with no self-custody exit. The Global Account runs on Bridge with banking through Lead Bank, Member FDIC. That coverage applies to the banking rails. KAST's digital-asset balance itself is not FDIC-insured. The cardholder agreement names Third National as the card issuer.
The app operator, KAST Tech, is incorporated in Anjouan, Comoros. The cardholder agreement names Troia Corp as the card-program entity. No documented pattern of frozen balances or stuck withdrawals surfaced during the audit period, although that does not guarantee future access to funds. The issuer being disclosed strengthens the custody picture, but the offshore KAST Tech/Troia structure and the uninsured digital-asset balance remain risks for anyone holding a balance.
UX, App, and Support
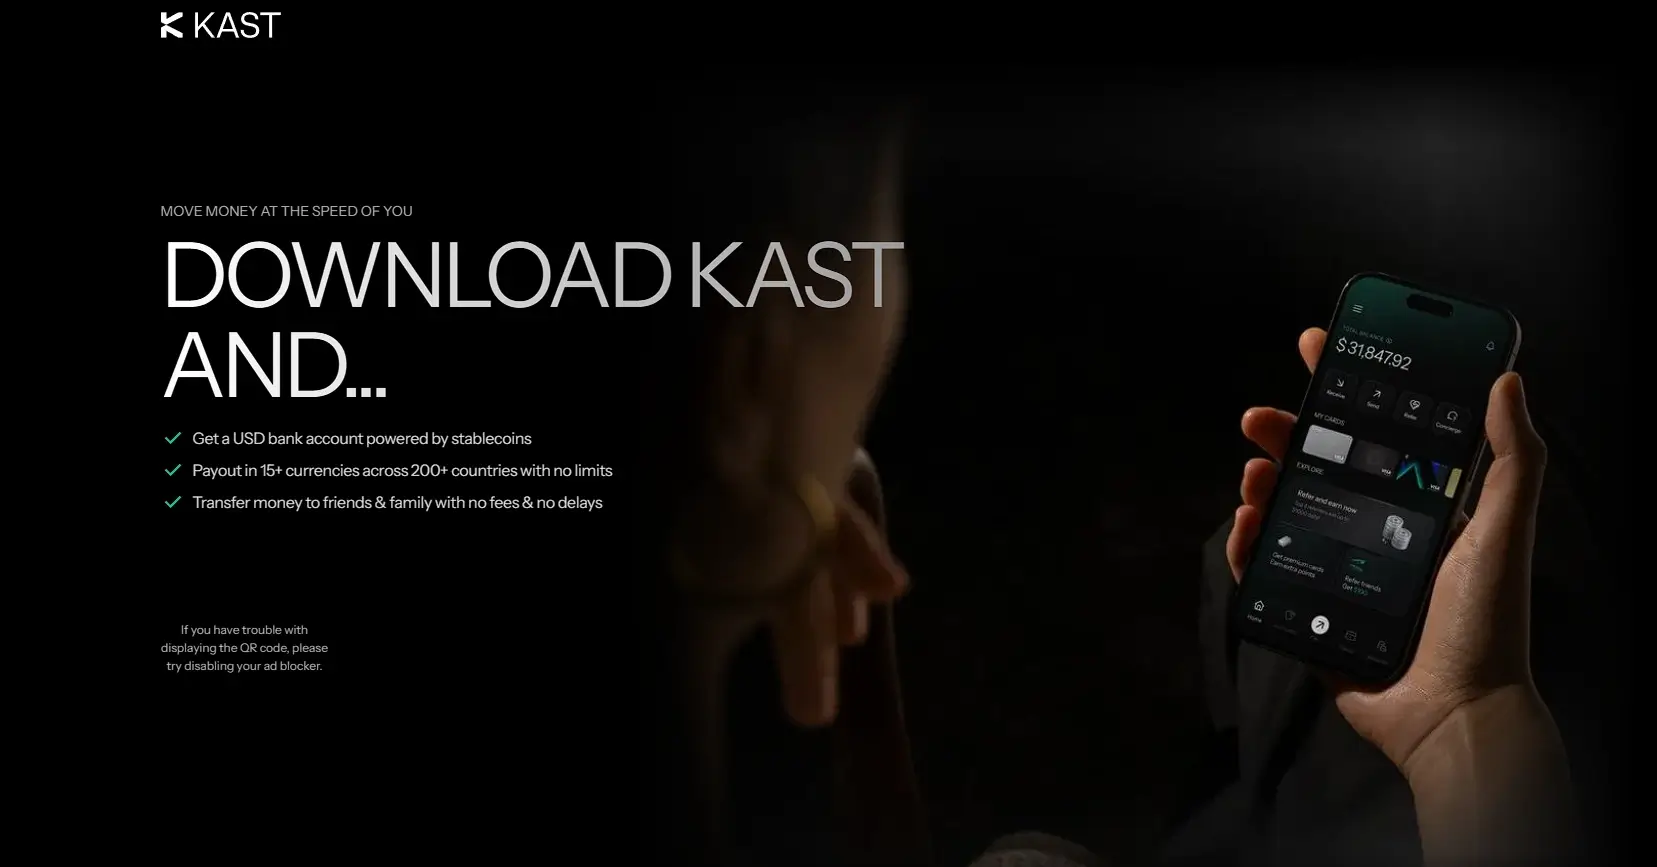
The app handles KYC and issues a virtual card within minutes. Users can freeze cards, link Apple Pay or Google Pay, and deposit or withdraw stablecoins. Transfers to other KAST users are instant and free up to $10,000 a day. Physical cards upgrade the form factor by tier, from plastic on Standard to metal and a gold card on Private.
Support is in-app and web-based, with 24/7 concierge coverage advertised. KAST does not disclose chargeback fees or dispute timelines. Testing support with a small balance can help assess its response before committing more money.
Tax and Record-Keeping
Purchases draw on a USD balance without selling crypto at checkout. Stablecoin deposits convert at 1:1, leaving negligible gain or loss to report. Depositing BTC, ETH, SOL, XRP or BNB creates a disposal when KAST buys the asset. Cashback may also count as income, depending on jurisdiction.
KAST does not disclose CSV export, cost-basis tracking, or tax-software integration. Cardholders reconciling disposals from volatile-crypto deposits need to keep their own records of what was sent and the USD value credited.
KAST Alternatives
-

RedotPay
RedotPay lets eligible users preload crypto and spend through its card. Standard has no recurring purchase cashback. Optional Pro adds capped rewards on eligible Apple Pay and Google Pay payments for a...
-
Crypto.com Card
Crypto.com offers a US credit card and a separate prepaid Visa with different fees and rewards. The flagship is now a Comenity credit card that earns cashback on a revolving line with...
KAST combines fast stablecoin spending with broad delivery coverage. The alternatives below differ in custody and regional access, as well as funding costs and rewards.
| Alternative | Why Someone Would Choose It Instead |
|---|---|
| MetaMask Card | Funds stay in the MetaMask wallet until payment, offering a stronger self-custody fit for users who do not want assets converted on deposit |
| RedotPay | Built around stablecoin spending with no annual fee; the trade-off is issuance fees of $10 for a virtual card and $100 for a physical card, plus a custodial model |
| Crypto.com Card | Broader reward and rebate programs, easier fiat top-up options, and a more mature card stack, with the trade-off being CRO exposure and a tiered staking model |
KAST suits users who need a virtual card quickly and want to fund it with stablecoins across many countries. Users prioritizing self-custody or lower transaction costs should compare the alternatives. Dollar cashback and KAST Points should also be assessed separately.
Final Verdict
KAST converts stablecoin deposits into a USD Visa balance at 1:1 with no spread. It works in 170+ countries including the US, issues a virtual card minutes after a two-minute KYC check, and pays 1.5% in dollars on its free membership. This score reflects the May 2026 membership model. The 8% points offers attached to the retired Limited and Luxe cards no longer apply. The free tier's cashback is capped at $30 a month. Foreign-currency purchases cost 0.5% to 1.75%, ATM withdrawals cost $3 + 2%, and volatile-crypto deposits cost 2% to 5%. Those fees reduce the value for travelers and BTC holders. KAST Tech operates the app from Anjouan, while Troia Corp runs the card program. The cardholder agreement names Third National as issuer, but the digital-asset balance remains uninsured. The card's lowest-cost use is stablecoin funding followed by dollar spending. Anyone funding it with volatile crypto needs to account for the deposit charge before comparing rewards.
Disclaimer: CryptoSlate may receive a commission when you click links on our site and make a purchase or complete an action with a third party. This does not influence our editorial independence, reviews, or ratings, and we always aim to provide accurate, transparent information to our readers.