Bab el-Mandeb Strait effectively closed by…?
Current Odds
Odds Summary
December 31 leads at 16% reported probability on Polymarket.
Polymarket · Last synced
Market Analysis
Bab el-Mandeb Curve Favors Acute Shock Over Gradual Closure
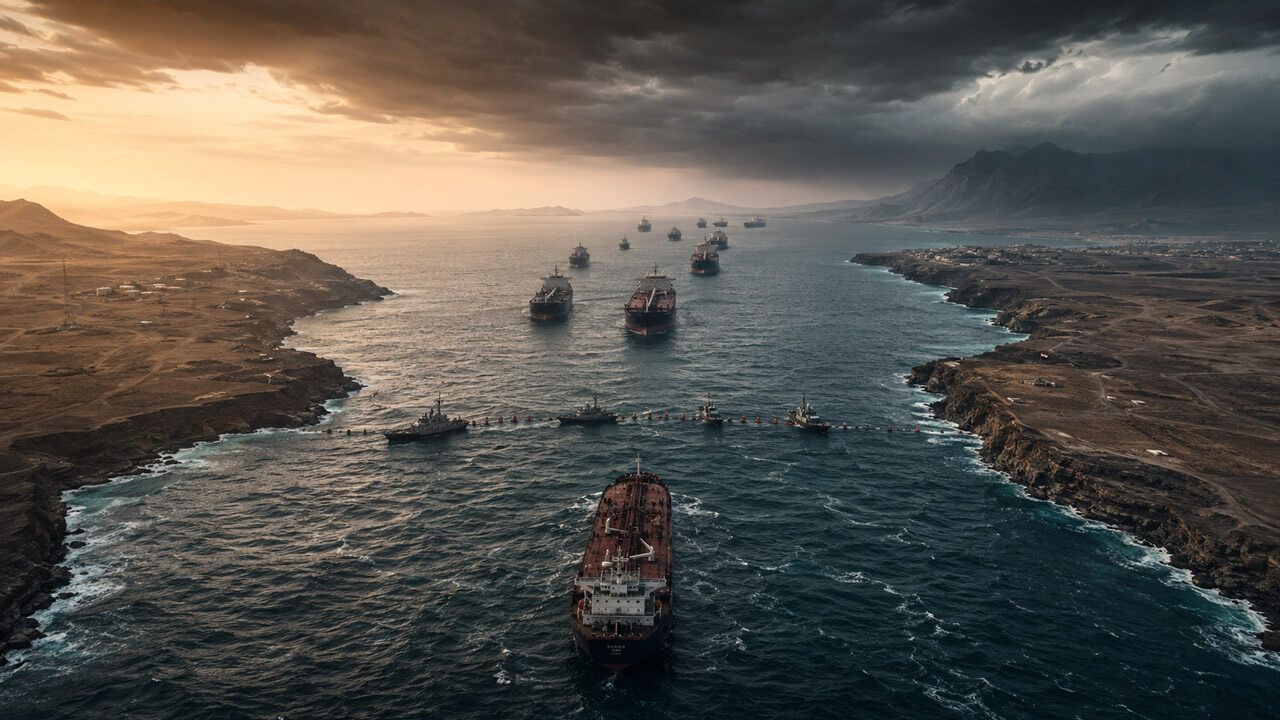
The rising deadlines encode a front-loaded hazard: an acute disruption has the clearest near-term path to the IMF’s traffic threshold, while later contracts accumulate additional routes to settlement. The decisive issue is sustained measured ship scarcity, regardless of whether authorities formally declare the strait closed.
The price hierarchy implies that a closure-scale event is most plausible as a sudden operational shock, with progressively smaller additions from prolonged attrition. July 31 is priced at 10%, August 31 at 19%, September 30 at 23.5%, and December 31 at 33.5%. Because each contract covers the period from market creation through its deadline, the meaningful signal lies in the gaps between dates. Those gaps favor an early shock over a steadily intensifying path through year-end.
The curve concentrates hazard in July and August
The nine-point increase from July to August implies roughly a 10% conditional probability of first crossing the threshold during August, given no qualifying reading by July 31. September adds 4.5 points, equivalent to about 5.6% conditional on no earlier settlement. December adds another 10 points across three months, or approximately 13.1% conditional on surviving September.
These are market inferences from quoted prices, rather than independent forecasts. They suggest that the first two monthly windows carry a higher hazard rate than the autumn extension. The December contract’s 33.5% price therefore should not be read as a forecast concentrated in December; most of its probability is inherited from earlier deadlines.
PortWatch’s threshold separates closure language from settlement
The rules define effective closure through one observable: IMF PortWatch must publish a seven-day moving average of Bab el-Mandeb transit calls, labeled “Arrivals of Ships,” at or below 10. A government declaration, naval warning, attack, obstruction, or carrier announcement has settlement relevance only through its effect on that published average.
This creates two hidden assumptions. First, disruption must be deep or persistent enough to pull a rolling average through 10. An isolated low-traffic day may have little effect if surrounding days remain active. Second, a qualifying reading could arise without a formal closure. Hypothetical causes include widespread voluntary rerouting, physical blockage, sustained attacks, military restrictions, or operating decisions that sharply reduce transits.
The missing traffic baseline limits geopolitical conclusions
The supplied record provides the threshold and settlement source, but no current PortWatch reading or recent trend. That missing baseline determines how much disruption is required. A moving average already near 10 would make modest additional rerouting consequential. A reading far above 10 would require a larger and longer shock.
Evidence favoring the market’s near-term hierarchy would include several consecutive weak daily observations that pull the seven-day series toward the threshold. Stable readings comfortably above 10 would weaken the acute-shock thesis, even amid elevated regional rhetoric. The metric’s trajectory carries more direct resolution value than broad descriptions of maritime tension.
Concrete catalysts must alter a full seven-day path
The clearest repricing catalysts would be events capable of changing multiple consecutive traffic observations:
- A physical obstruction, sustained attack campaign, or enforceable maritime restriction that interrupts passage.
- Documented carrier rerouting broad enough to reduce total transit calls for several days.
- PortWatch readings approaching 10, especially when the weakest observations begin filling most of the rolling window.
- Restored transits, security arrangements, or carrier resumptions that replace low observations before the average crosses the threshold.
A PortWatch publication at or below 10 would settle every contract whose deadline includes that date. A dramatic event followed by rapid traffic recovery could still fail to qualify because the seven-day averaging rule filters brief disruptions.
Cumulative exposure is the main counter-signal
The strongest alternative explanation is simple elapsed time. Later contracts contain every earlier route to settlement plus additional days, so rising prices do not by themselves establish expectations of worsening conditions. The 10-point increase from September through December spans roughly three times the calendar exposure of either preceding monthly step, reinforcing the interpretation that marginal hazard declines after summer.
Aggregate activity gives the curve some informational weight: the event reports $6.31 million in volume, $248,110 in liquidity, and $667,220 in open interest. Those totals cannot establish that each deadline is equally liquid or that buyers possess superior information. The June 30, 2026 market close also should not be confused with the qualifying windows, which end on each contract’s listed date. Fresh PortWatch data remain the evidence most capable of separating a geopolitical narrative from a settlement-relevant traffic collapse.
Sources
What Could Move the Odds?
Market-Implied Thesis
The curve implies a limited but rising chance that arrivals hit the ≤10 trigger by later deadlines, not that the strait is already closed.
Higher later-dated Yes prices price additional time for a disruption to drive the PortWatch seven-day average below the contract’s threshold.
What Could Reprice It
A renewed Houthi attack or broader vessel targeting that suppresses traffic enough to register in PortWatch’s rolling arrivals data is the key repricing channel.
The U.S. Maritime Administration describes continuing high risk for certain vessel affiliations; expansion beyond targeted traffic could affect the settlement metric quickly.
Where the Market May Be Weak
The contract measures a data threshold, not a legal or physical closure, so a rerouting-driven dip could settle Yes without proving the strait was closed.
Its any-date rule makes a single qualifying seven-day average decisive, creating a gap between the headline’s “effectively closed” framing and settlement.
Counter-Signal
PortWatch is described as far from the ≤10 threshold, while reported threats target selected affiliations, leaving broad transit possible despite escalation.
PortWatch’s satellite-based coverage supports timely measurement, but Yemen coast control and heightened attacks do not by themselves establish a system-wide collapse in arrivals.
Market Details
- Resolution criteria
- This market will resolve to “Yes” if IMF PortWatch publishes a 7-day moving average of transit calls (“Arrivals of Ships”) for the Bab el-Mandeb Strait less than or equal to 10 for any date between market creation and the listed date. Otherwise, this market will resolve to “No”.
- Platform
-

- Category
- Politics › Middle East
- Scheduled deadline
- January 1, 2027, 4:59 AM UTC
- Settlement source
- portwatch.imf.org
- Market rules summary
- Multi-timeframe Polymarket event. Each listed timeframe is represented by its Yes price on the underlying binary market. View full rules
Frequently Asked Questions
What are the current Bab el-Mandeb Strait effectively closed by… odds?
Polymarket reports Bab el-Mandeb Strait effectively closed by… odds with December 31 at 16%, November 30 at 10.5%, and October 31 at 2%. These probabilities are market-implied and can change as liquidity and trading activity update. The latest market snapshot includes $17.48M volume, $350.15K liquidity, and $1.17M open interest. CryptoSlate last synced this market data at Oct 23, 2026, 07:12 UTC.
What could move the Bab el-Mandeb Strait effectively closed by… prediction market odds?
The curve implies a limited but rising chance that arrivals hit the ≤10 trigger by later deadlines, not that the strait is already closed. Higher later-dated Yes prices price additional time for a disruption to drive the PortWatch seven-day average below the contract’s threshold. Catalysts to watch include A sharp, sustained fall in PortWatch arrivals, Expanded attacks or targeting near Bab el-Mandeb, and Any qualifying PortWatch observation.
How does the Bab el-Mandeb Strait effectively closed by… prediction market resolve?
This market will resolve to “Yes” if IMF PortWatch publishes a 7-day moving average of transit calls (“Arrivals of Ships”) for the Bab el-Mandeb Strait less than or equal to 10 for any date between market creation and the listed date. Otherwise, this market will resolve to “No”. Multi-timeframe Polymarket event. Each listed timeframe is represented by its Yes price on the underlying binary market. The settlement source listed for this market is Portwatch.
Related Middle East Markets
 Israel withdraws from Lebanon date
 Israel x Iran ceasefire continues through…?
 Netanyahu out by…?