


- Top up with mobile money as well as crypto
- Balances in EUR, USD, GBP, MXN and BRL
- Unlimited virtual cards to split merchants
KemyCard Overview
- Crypto Card Name
- KemyCard
- Card Type
- Prepaid
- Network
- VisaMastercard
- Digital Wallets
- Apple Pay, Google Pay, Samsung Pay
Additional details
- Availability
- Varies By Jurisdiction
- Rewards
- No rewards.
- Fees
- $15 virtual or $250 physical issuance, including DHL delivery for physical cards. Monthly fee: $2 virtual or $10 physical. Card top-ups: $1.50 below $100, otherwise 1.25%. Purchase fee: 3.5% + $1. Main-account deposit fees are additional and the official page gives conflicting 5% and 8% figures.
- Daily Spend / ATM Limit
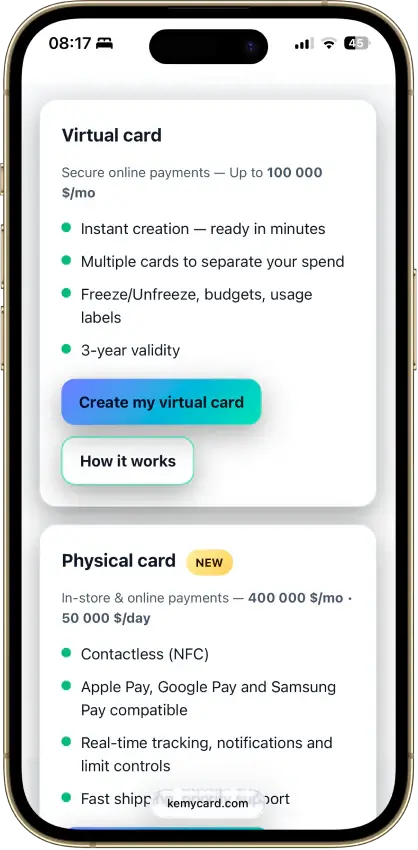
- Virtual: $10,000 per transaction and $100,000 maximum balance. Physical: $25,000 per transaction, $50,000 daily spend and $400,000 maximum balance. Physical ATM limits: $500/day and $15,000/month.
- Funding Source
- On-chain Wallet
- Virtual Card & Shipping
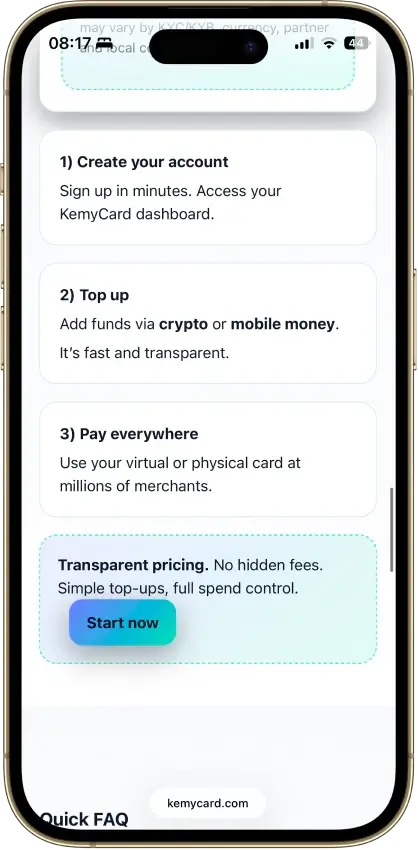
- Virtual card creation takes a few minutes. Physical card delivery uses DHL Express.
KemyCard Screenshots
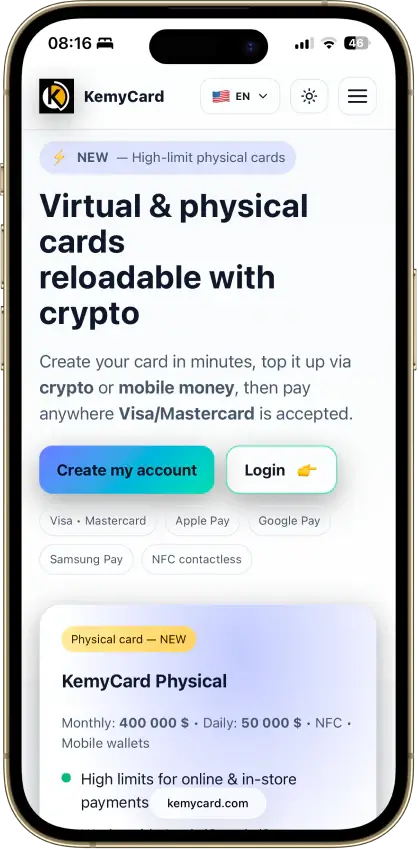
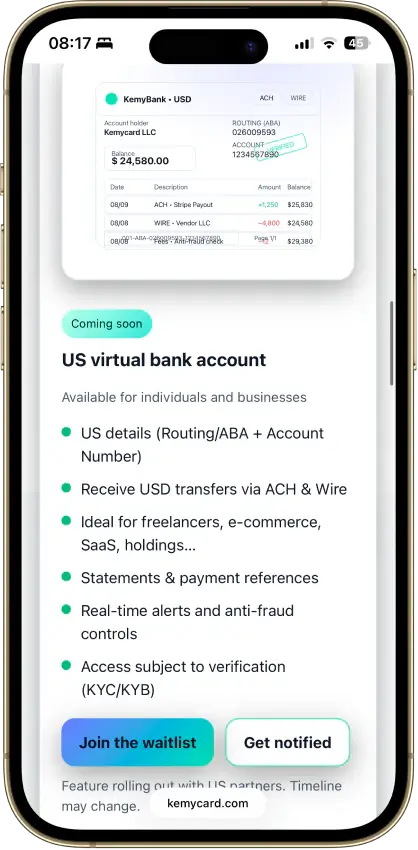

Screenshot 1 of 8
KemyCard Pros and Cons
Pros
- Virtual card issues within minutes
- Apple Pay, Google Pay and Samsung Pay
- High spend limits on the physical card
- Instant freeze and unfreeze controls
- Cards run from a web dashboard or Telegram bot
Cons
- Owners and issuing bank never identified
- Sells full eKYC and "no KYC" at once
- 8% deposit fee, 3.5% plus $1 per purchase
- ATM and FX fees not disclosed
- No cashback or rewards
Who KemyCard Is Best For And Who Should Skip It
Users drawn by the $400,000 physical-card balance ceiling increase the amount held with a custodian whose owners and issuing bank are undisclosed. Users chasing the no-KYC pitch are trusting a company that simultaneously claims full eKYC and real-time AML monitoring. Those statements leave the actual verification requirement unclear.
Other cards offer stablecoin spending for $0 monthly. KemyCard provides no disclosed FX rate and earns zero cashback, so travelers and reward-seeking users have little basis to choose it over a card with a named issuer and published fees.
What This Card Actually Is and How Spending Works
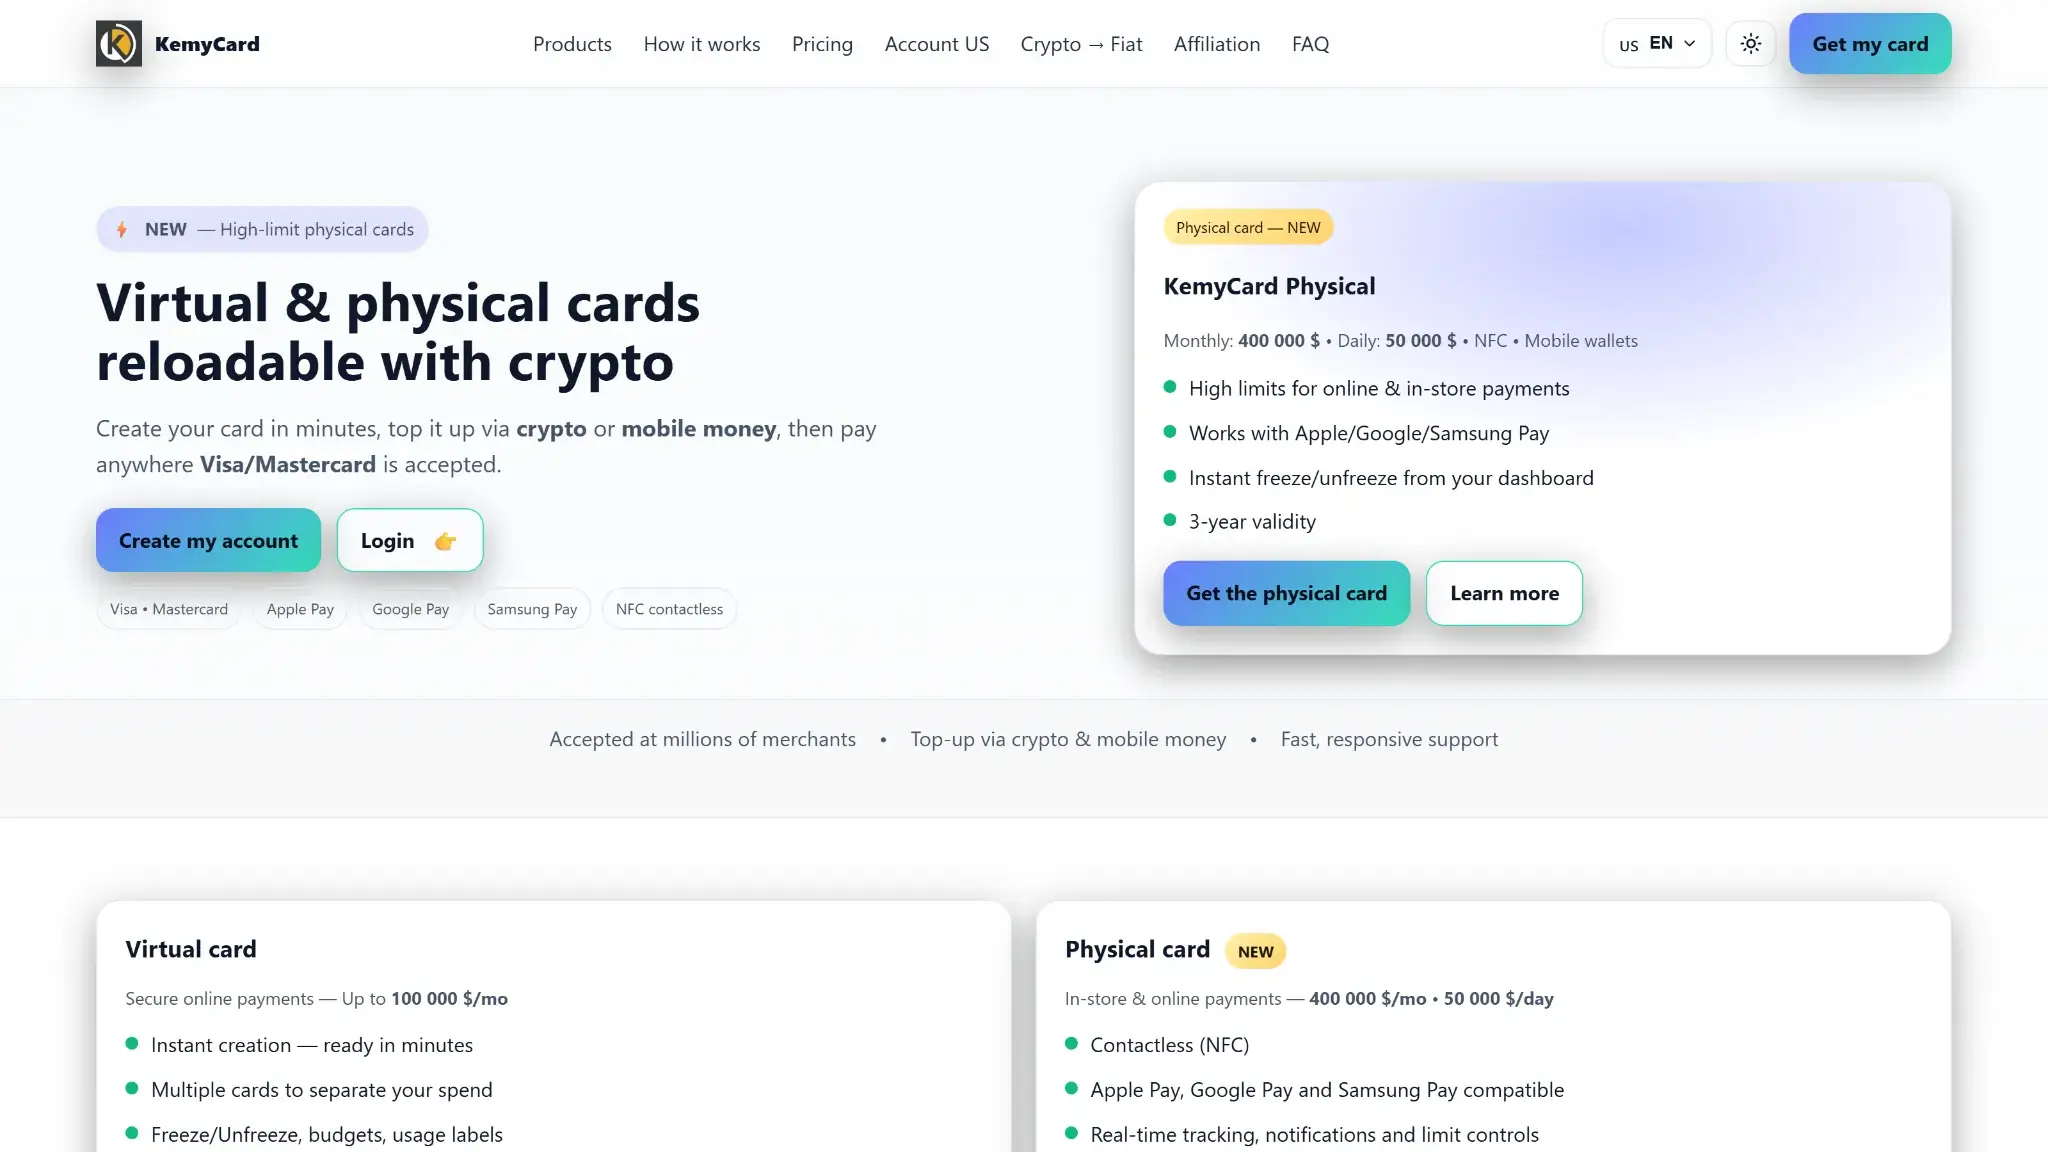
KemyCard requires users to fund a balance with crypto or mobile money first, then spend the balance at card terminals and online checkouts. There is no credit line and no linked bank account behind it. Conversion occurs when the balance is loaded, along with any taxable disposal. Subsequent purchases draw on the converted balance without another sale.
The platform operator is Kemite Group, LLC, a registered Delaware entity with a published Dover address. No individuals behind the company are named. The bank that issues the cards and holds cardholder funds is described only as “authorized banking partners” operating under licenses from Visa U.S.A. Inc. and Mastercard International, with no institution named. Other crypto cards identify issuers such as Pathward, Cross River and DiPocket. KemyCard provides no equivalent bank name for a reader to verify.
The site advertises Visa and Mastercard across its products but does not identify the network assigned to each tier.
Rewards Mechanics
KemyCard's reward rate is 0% across all tiers, with no cashback or rebates. Its incentive payments go to promoters through the programs below.
| Element | Value | Notes |
|---|---|---|
| Base rate | 0% | No cashback, perks, or rebates at any tier |
| Referral bounty | $5–$25 per card | Paid for each card a recruit creates |
| Referral override | 1% of recruit top-ups | Paid on that recruit's top-ups |
These bounties reward the promoter who recruits a cardholder. They are not purchase rewards for the cardholder.
Fees and Pricing
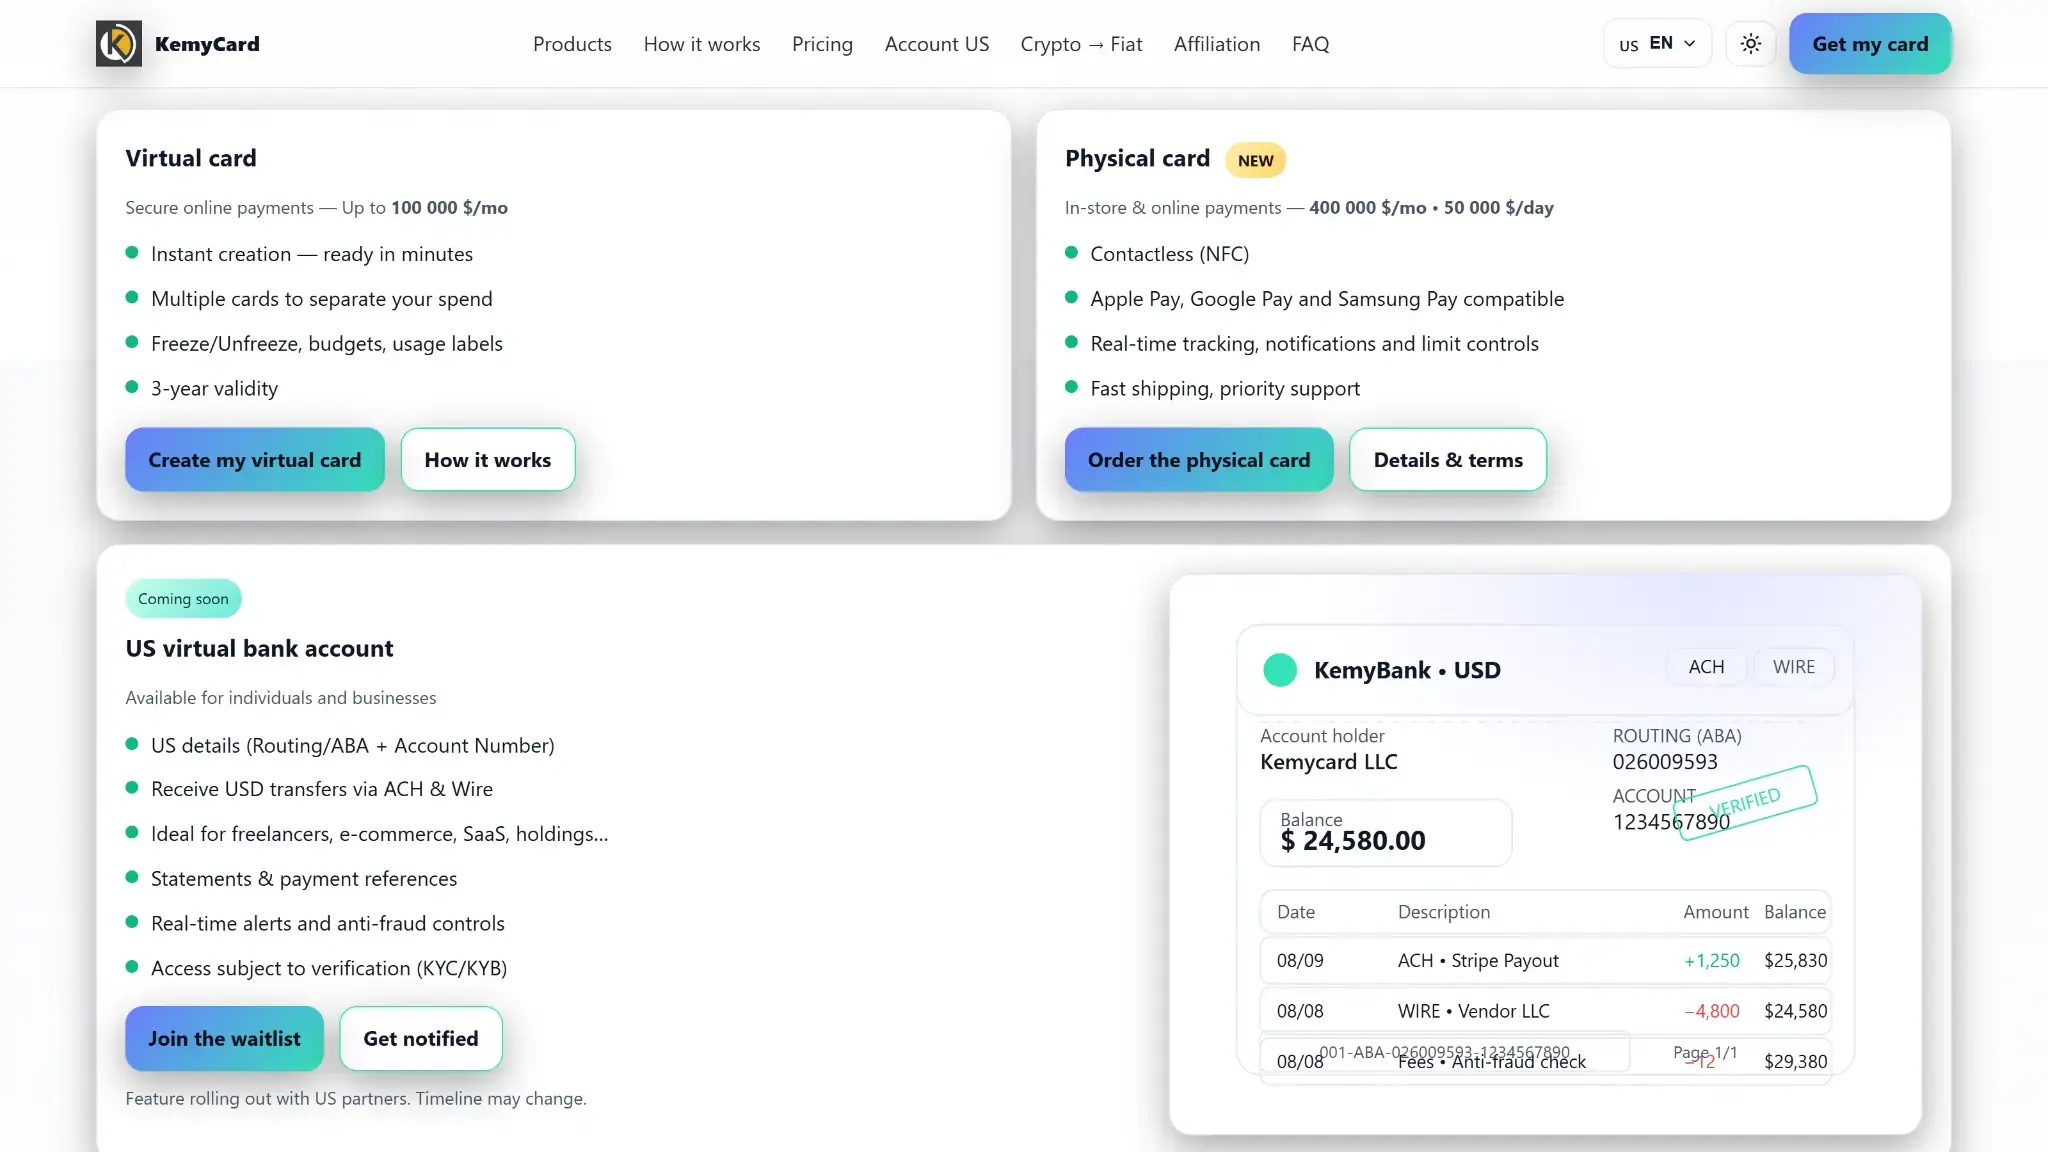
KemyCard's pricing summary lists an 8% deposit fee, while a detail section on the same page says 5%. The calculation below uses 8% because the site leaves that conflict unresolved. Despite the homepage's “No hidden fees” claim, no ATM or FX schedule is published.
| Fee | Amount |
|---|---|
| Deposit (crypto or mobile money) | 8% (5% elsewhere on the same page) |
| Virtual card issuance | $15, valid for three years |
| Physical card issuance | $250, DHL Express shipping included |
| Monthly fee | $2 virtual, $10 physical |
| Card top-up | $1.50 under $100, 1.25% at $100+ |
| Purchase transaction | 3.5% + $1 |
| Failed transaction | $0.80 |
| ATM withdrawal | Not disclosed |
| FX conversion | Not disclosed |
At the quoted 8% rate, a $500 crypto deposit incurs a $40 charge. Moving the remaining $460 onto a fresh virtual card costs $15 issuance plus $5.75 in top-up fees. A single $200 purchase adds $8, and the $2 monthly fee starts immediately. That is roughly $71 in fees to spend $200, before ATM or currency conversion charges and network gas. Those additional costs are not disclosed before payment.
Limits, Purchase and ATM
| Limit | Virtual | Physical |
|---|---|---|
| Per transaction | $10,000 | $25,000 |
| Daily spend | Not disclosed | $50,000 |
| Monthly spend | Not disclosed | $400,000 |
| Balance ceiling | $100,000 | $400,000 |
| ATM daily | — | $500 |
| ATM monthly | — | $15,000 |
| Minimum top-up | $5 | $10 |
Using the full $400,000 ceiling leaves that amount with a custodian whose issuing bank and owners are undisclosed. ATM withdrawals are capped at $500 daily, with the fee undisclosed. Refund and reversal timing is not disclosed either, so declines and merchant reversals are impossible to plan around.
Eligibility and Availability
KemyCard accepts new applicants and advertises availability in 190+ countries, qualified by this statement. “A few restrictions apply — sign up to check if your country is supported.” Eligibility is discoverable only after handing over signup details.
The website's security section claims full eKYC, meaning automated ID and biometric verification through Sumsub and Veriff with real-time AML monitoring. The same website's Telegram section issues cards with “No KYC — start instantly,” and reseller listings across BlackHatWorld, Bitcointalk, OffshoreCorpTalk, and Telegram sell the card as no-KYC with fake profile details accepted. Those claims conflict and do not establish which verification process a new applicant will face.
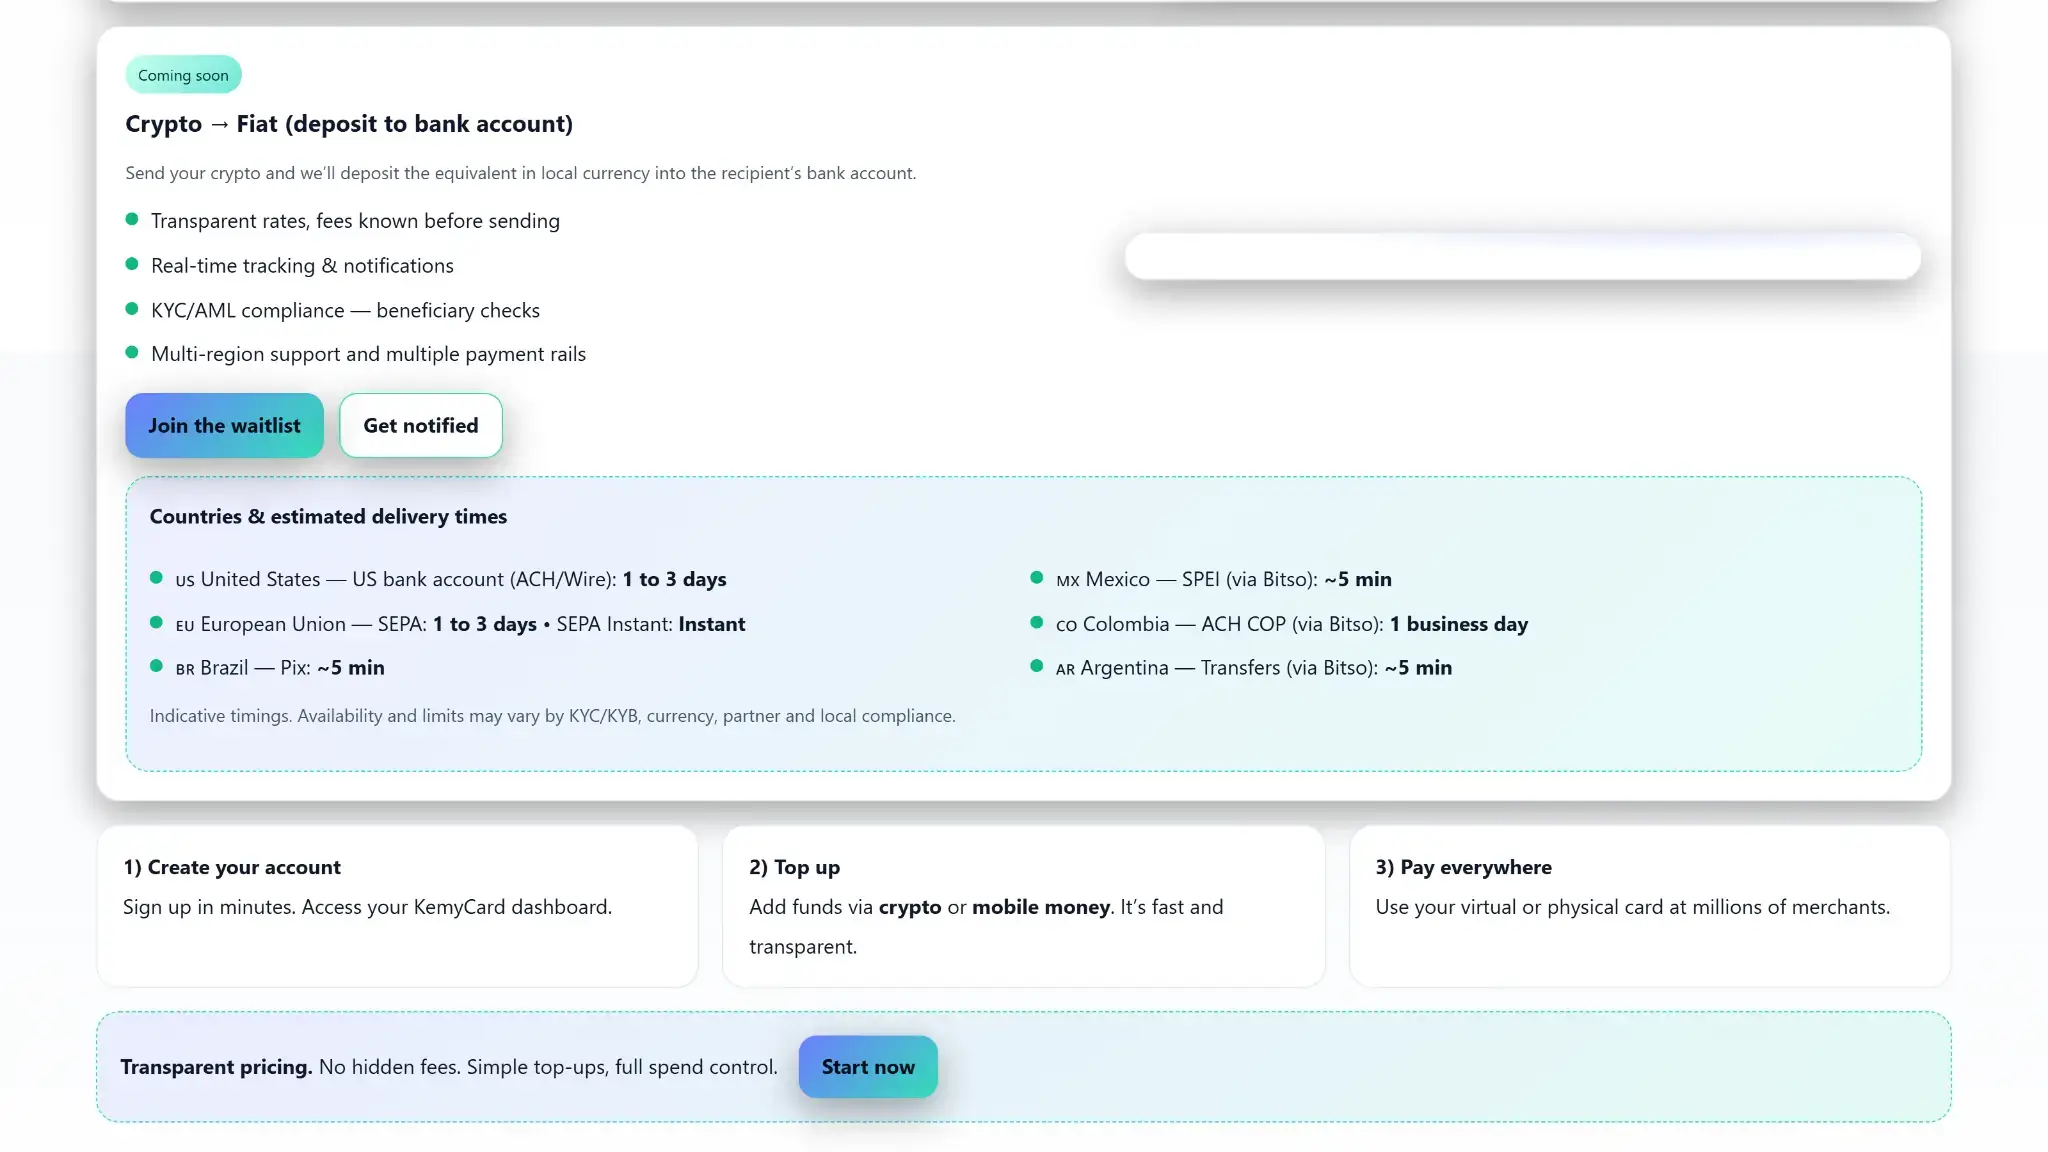
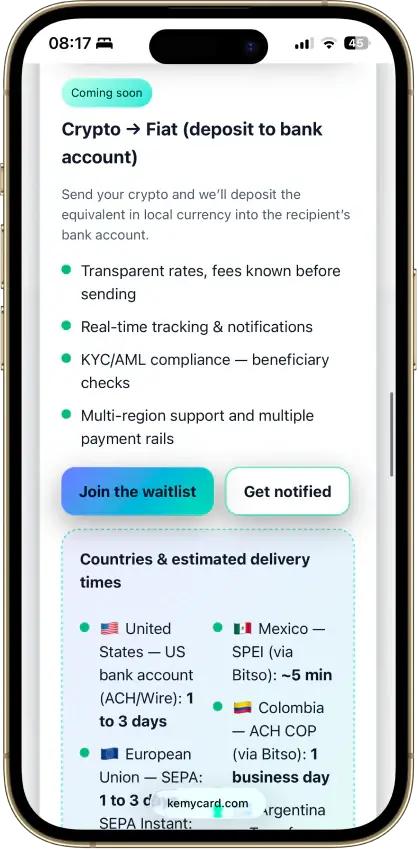
The USD virtual account and ACH, wire and SEPA payout services are labeled “coming soon.” Those planned bank features do not establish current US card eligibility. Third-party directories and reseller ads describe a US BIN obtainable by US residents today. Whether a US applicant can complete signup end-to-end is unconfirmed, so the card's advertised US access should not be treated as verified.
The site also states KemyCard is “a Money Services Business (MSB) licensed by the Financial Crimes Enforcement Network.” FinCEN does not license anyone. MSB registration is a self-filed form under the Bank Secrecy Act that carries no vetting, audit, or endorsement, and even the registration itself is unconfirmed for Kemite Group, LLC. Describing a self-filed registration as a government license misrepresents what it is.
Restricted Countries
KemyCard publishes no restricted-country list on its homepage, terms or pricing page. It says only that “a few restrictions apply.” For a product claiming 190+ countries, that means no reader anywhere can confirm eligibility without creating an account first, and no exclusion list is provided by the company.
Funding Rails
The prepaid balance can be funded with crypto or mobile money. Third-party reporting names Cryptomus as the gateway, although Kemy's own pages do not identify the processor. The home page lists USDT, USDC, BTC, ETH, and SOL plus “more” without a canonical asset-and-network list, so a depositor has to confirm the chain inside the dashboard before sending. A wrong-network transfer is unrecoverable. Reseller listings name a wider set (LTC, DOGE, TRX, XMR, and BNB among them), none of it confirmed on an official page.
Stablecoins are the cleanest route in, since a 1:1 load avoids a conversion spread on top of the 8% fee. Balances display in EUR, USD, GBP, MXN, and BRL. The USD account and crypto-to-fiat payouts remain “coming soon,” leaving no live off-ramp for loaded funds. The balance must be spent through the card or remain in the account. 2025 Trustpilot reviews describe deposits held in AML review. KemyCard attributed those holds to its payment processor.
Security, Custody, and Freeze Risk
The available evidence leaves several questions about custody and access to funds.
- The operator's people are undisclosed. Kemite Group, LLC is a registered Delaware entity (registration #20250007719) with a published Dover, DE address, but no founder, executive, or beneficial owner is named anywhere, and domain WHOIS is private.
- The custodian is unverifiable. The site says funds are “held with regulated financial institutions” in segregated accounts with regular audits, and names none of the institutions and no auditor. A claim with no counterparty attached cannot be checked.
- Independent scanners flag the domain. Scamadviser rates kemycard.com “Likely Unsafe,” citing a registrar popular with scammers and mainly negative reviews. Scam-Detector scores it low as well.
- Reseller listings promote bypassing verification. “No KYC, fake info OK, BIN USA” listings, backed by a per-card bounty, run in the same channels the company's own Telegram bot serves.
- Deposit holds are on record. 2025 Trustpilot complaints describe blocked deposits, disabled cards, and slow resolutions, with the company offering manual credits or replacement cards in its responses.
These reports do not establish fraud. They do leave the custodian unidentified and the operator's claims difficult to verify, alongside documented complaints about access to funds. Fees are non-refundable once service is activated, and there is no published penalty or account-restriction schedule to appeal against.
UX, App, and Support
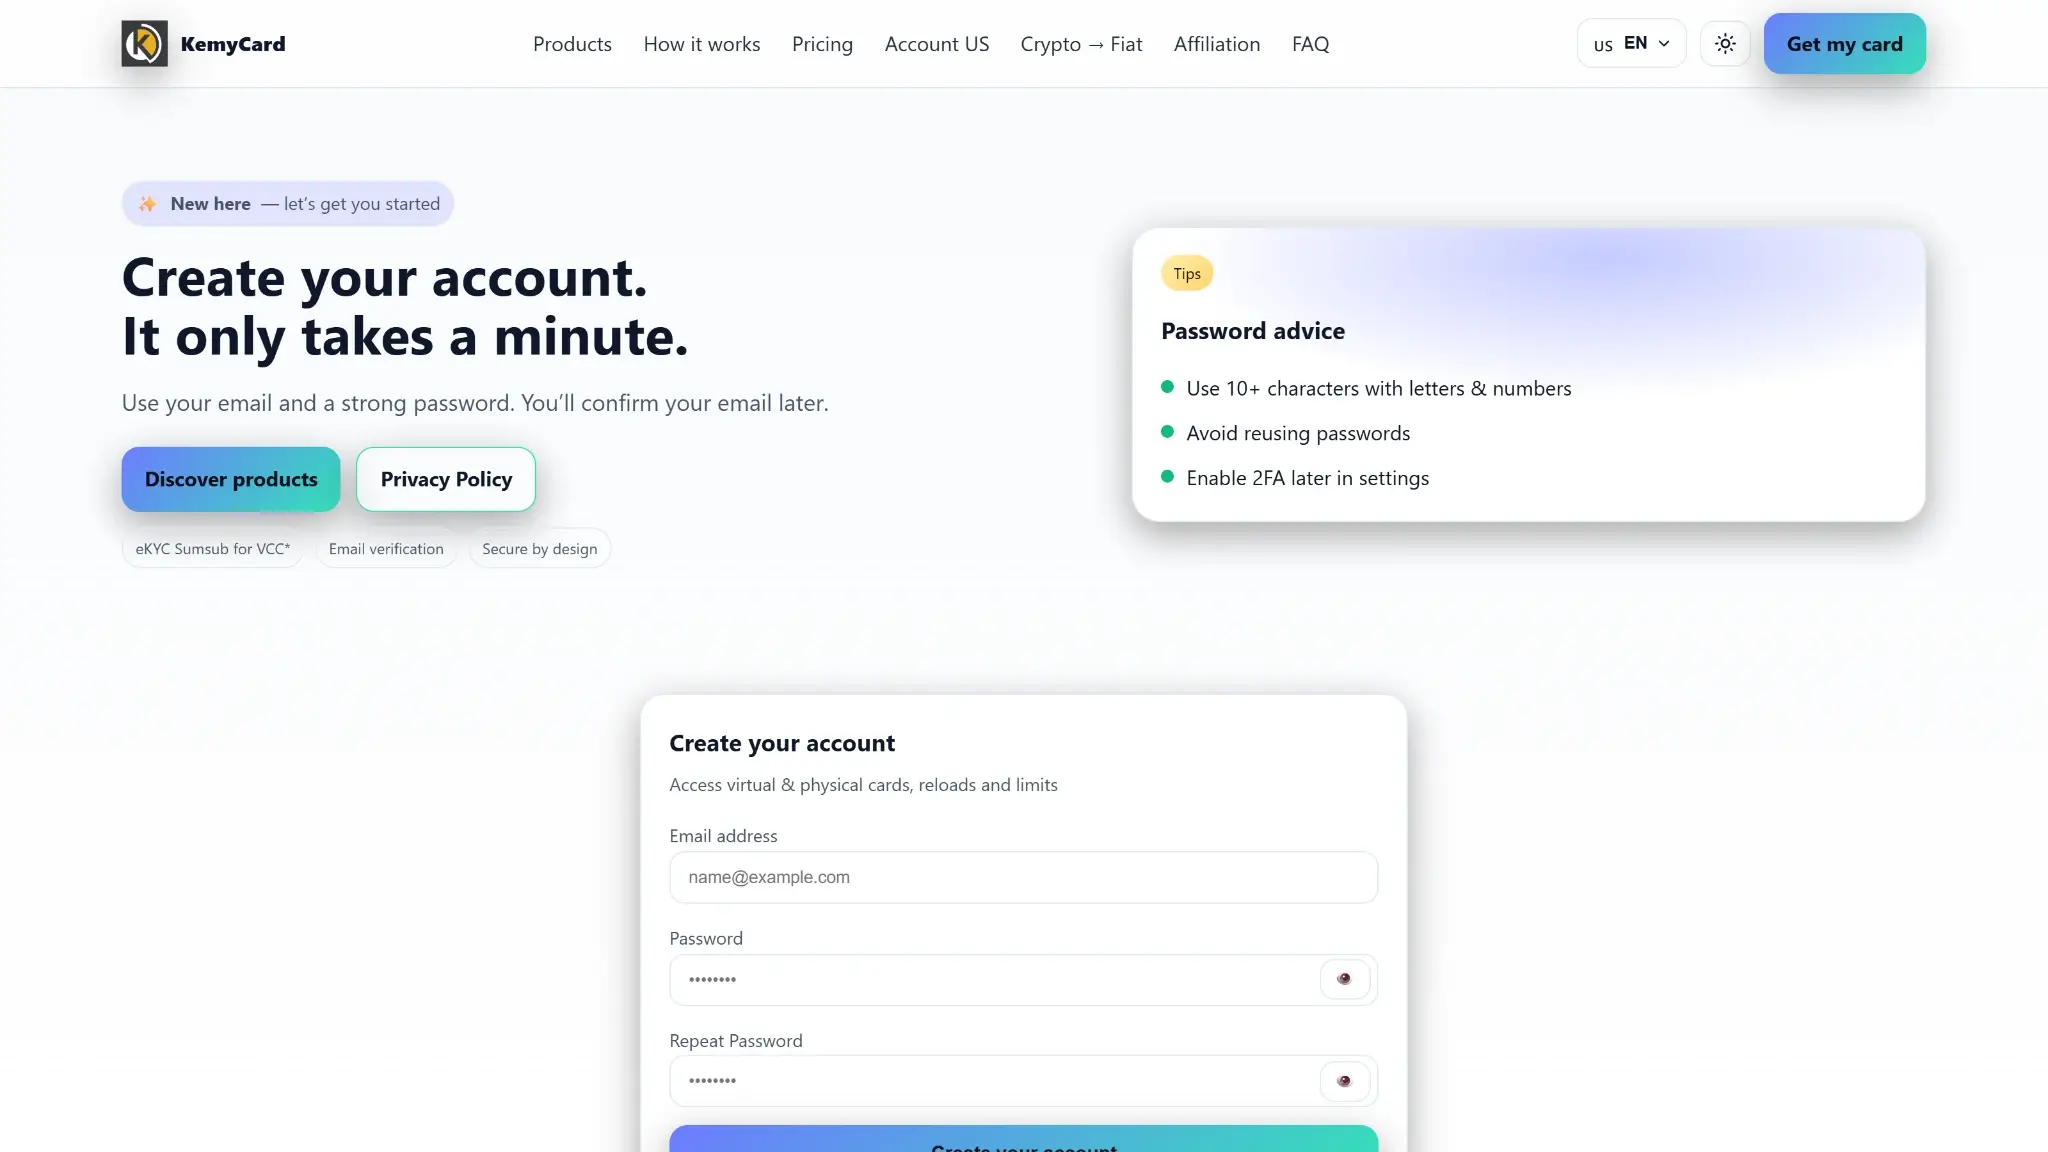
The product runs through a web dashboard and the @KemyCardBot Telegram bot. The dashboard advertises instant card freezes, unfreezes and deletion. Unlimited virtual cards can separate merchants and subscriptions, while the physical card supports Apple Pay, Google Pay and Samsung Pay. Physical delivery is quoted at 5 to 15 business days by DHL Express.
Support is reachable through a help center, live chat with unstated hours, email, and Telegram. Chargeback rights and refund timing remain undisclosed. There is also no published escalation route for a frozen balance. The complaints on record cluster exactly where support has the least reach, in the gap between the payment processor, the unnamed issuer, and the operator.
Tax and Record-Keeping
Converting crypto to fund the card can create a taxable disposal, depending on jurisdiction. Purchases then draw on the fiat balance without another sale. Stablecoin loads reduce price volatility but still require transaction records. KemyCard discloses nothing about statements, CSV export, or cost-basis records, so cardholders track deposits, conversions, spends, failures, and refunds by hand.
KemyCard Alternatives
-

Kast Card
KAST turns a stablecoin balance into a spendable USD Visa that works in 170+ countries, including the US that most crypto cards skip. Stablecoins load 1:1 without a spread. A virtual card...
-
RedotPay
RedotPay lets eligible users preload crypto and spend through its card. Standard has no recurring purchase cashback. Optional Pro adds capped rewards on eligible Apple Pay and Google Pay payments for a...
-
Bybit Card
Bybit Card spends from a Funding Account, but rewards depend on the regional program. Bybit EU offers an uncapped 1% non-VIP base rate. Other Bybit programs use a capped 2%–10% tier schedule...
A different card can still make more sense if you care more about stablecoin support, self-custody, rewards, or lower recurring fee drag than raw spend limits.
| Alternative | Better For | Why Someone Would Choose It Instead | Main Trade-Off |
|---|---|---|---|
| KAST Card | Stablecoin spending and travel-friendly mobile-wallet use | Instant virtual card, Apple Pay and Google Pay support, broad country coverage, and local-currency conversion at checkout | Availability and plan economics still vary by jurisdiction |
| RedotPay | Stablecoin-first daily spend | Stablecoin payments sit at the center of the product, with card spend, transfers, and multi-currency app support in one place | Still custodial, and regional access or KYC friction can vary |
| MetaMask Card | Better self-custody fit | Funds stay in the MetaMask wallet until payment, which is a cleaner fit for those who do not want a prepaid custodial balance | Country rollout and compliance checks still limit access |
| Bybit Card | Stronger rewards and lower recurring fee drag | No monthly or annual fee is a cleaner starting point, and cashback offers are stronger than KemyCard’s zero-reward model | Exchange-linked setup and regional availability can be limiting |
KemyCard's main advantage is high stated limits and card-format flexibility. Cheaper funding, rewards, self-custody, or a more transparent fee structure all point to other cards.
Final Verdict
KemyCard's physical card allows balances up to $400,000, but the operator does not name its beneficial owners or issuing bank. Conflicting verification claims and Scamadviser's “Likely Unsafe” rating further weaken the evidence for trusting it with a balance. The fee schedule adds an 8% deposit charge and 3.5% + $1 per purchase, alongside monthly fees. ATM and FX charges remain undisclosed, and there are no rewards to offset costs. High limits and fast virtual issuance do little to resolve those concerns. A named issuing bank and confirmed US signup path would make the card easier to assess. Published ATM and FX fees are also needed. These unresolved custody and pricing gaps underpin the Poor rating and prevent a recommendation in any market.
Disclaimer: CryptoSlate may receive a commission when you click links on our site and make a purchase or complete an action with a third party. This does not influence our editorial independence, reviews, or ratings, and we always aim to provide accurate, transparent information to our readers.